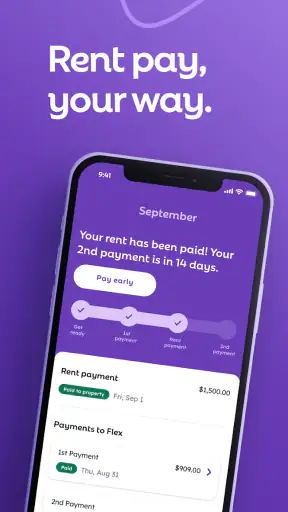
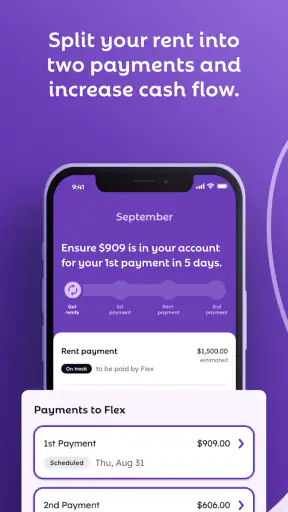
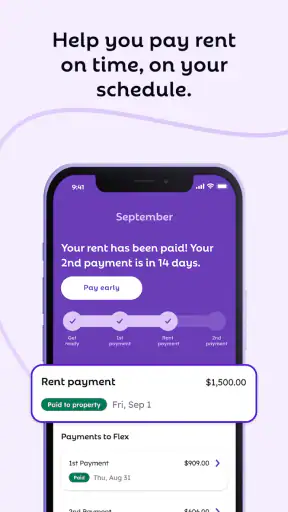
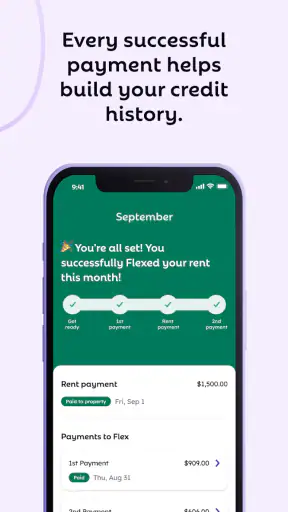
Managing rent is usually less stressful when the payment date is predictable, but the way people share housing can make that simple goal surprisingly difficult. Roommates may be paid on different days, couples may keep separate budgets, and someone moving between homes may need a little more flexibility than a standard monthly bill allows. Flex - Rent On Your Schedule is a finance app from Flexible Finance, Inc. built around that specific problem: helping users split rent on a schedule that fits their cash flow rather than forcing the whole amount into one familiar pattern.
After spending time with it, I see Flex as a focused tool rather than a complete household money manager. It is not trying to replace a budgeting app, a shared spreadsheet, or a bank account. Its value is narrower and more practical: it gives rent its own workflow. That distinction matters, because the app feels most useful when rent timing is the problem you are trying to solve. If you only need a reminder or a way to divide a bill once, a simpler alternative may be enough.
How Flex fits into a shared household
The most convincing use case is a household where the rent is stable but the people paying it are not. Imagine two roommates who receive income at different points in the month. One has money available near the beginning of the month, while the other has to wait until later. With a conventional rent arrangement, one person may cover the full payment temporarily, or both people may repeatedly negotiate who sends what and when. Flex is designed to make that timing less awkward by placing the rent schedule at the center of the experience.
That can also help someone who lives alone but has uneven income. A freelancer, hourly worker, or person with several pay cycles may find a single large rent payment harder to manage than a planned schedule. The important point is that changing payment timing does not make rent cheaper. I would treat the app as a cash-flow tool, not a discount service. The total obligation still needs to be understood clearly before relying on a more flexible arrangement.
For a shared device, I would be careful. A phone or tablet used by several members of a household is not the same thing as a shared household account. Finance apps sit close to sensitive personal information, so I would not casually leave an active session open for roommates, children, visitors, or anyone else who uses the device. Each person should understand whose account is active before opening the app, and I would use the device’s own privacy and account-separation options where available.
This is one of the first practical boundaries I noticed: Flex can support coordination, but it should not be treated as a public household dashboard. If three roommates need to see every person’s income, balances, and financial history, a shared budgeting document may be more appropriate for the coordination layer. Flex is better positioned as the rent-payment tool, while the household can use a separate, deliberately limited method to discuss responsibilities.
What the setup feels like in practice
The initial experience is less about exploring a large collection of financial tools and more about establishing a rent arrangement. That focused approach is welcome. I did not feel pushed through unrelated investment, credit, or spending features. The app’s purpose is easy to understand: connect the rent problem to a schedule that works for the user.
Still, the setup deserves more thought than simply tapping through screens. Before starting, I would gather the lease details, the normal rent due date, the amount that needs to be covered, and the names of the people who are actually responsible for paying. I would also decide whether Flex is being used by one tenant to manage their own obligation or as part of a roommate arrangement. That distinction prevents a common mistake: assuming that a payment schedule automatically explains who owes what inside the household.
The best setup is the one that separates payment timing from household responsibility. Flex may help organize when rent is handled, but roommates still need a clear agreement about shares, utilities, deposits, late changes, and what happens if someone moves out. I would write those decisions down before depending on the app. A short shared note can prevent arguments that no payment tool is designed to resolve.
There is also a useful habit here for people with irregular income. Instead of waiting until the due date to decide whether the schedule is affordable, I would map each planned rent contribution against the actual dates money arrives. That turns Flex into part of a broader cash-flow routine. Check the calendar at the start of the month, identify the tightest point, and leave room for ordinary expenses such as transport, groceries, and utilities. A flexible rent schedule should reduce pressure, not encourage someone to commit every available dollar.
Coordination between roommates and partners
Flex can make the timing conversation easier, but it does not remove the need for communication. In a shared home, I would agree on a simple rule before using it: who initiates the arrangement, who confirms the amount, and where everyone records their share. Without that rule, each person may assume another person is monitoring the payment.
A realistic example would be a pair of roommates with different paydays. The roommate with the earlier paycheck may prefer to handle the first part of the rent, while the other contributes later. They can discuss the arrangement in advance, then use Flex for the rent schedule while keeping a separate record of the split. If the second roommate also pays for internet or electricity, those bills should not be silently folded into the rent conversation. Keeping the categories separate makes it much easier to see whether the arrangement is still fair.
I also recommend agreeing on a backup plan. What happens if one person’s paycheck is delayed? What if a bank account changes, a roommate travels, or the lease is renewed with a different amount? A payment app cannot replace this conversation. The more dependent the household is on one person remembering every detail, the more fragile the arrangement becomes.
For couples, the decision is slightly different. Flex may be useful when partners share rent but keep separate accounts and want predictable coordination without merging all their finances. On the other hand, couples who already use a joint account and a shared budget may find that adding another rent workflow creates unnecessary duplication. In that situation, the bank’s scheduled payment tools or an existing budgeting app may be easier to maintain.
One non-obvious advantage of a dedicated rent app is psychological clarity. When rent is mixed into a general spending tracker, it can disappear among subscriptions, groceries, and discretionary purchases. A focused tool keeps attention on the largest recurring housing obligation. That can be valuable for a person who does not need a full financial system but repeatedly loses track of rent timing.
Account boundaries, age, and trust
Flex has an Everyone content rating, which makes the app broadly suitable from a content perspective. That should not be confused with financial independence for every age group. A young person may be able to understand the app’s interface while still needing an adult, leaseholder, or guardian to explain the legal and practical responsibility attached to rent.
I would be especially cautious when a teenager or young adult shares a phone with a parent or sibling. The app’s age rating does not create family permissions, shared approvals, or automatic separation between users. Those boundaries need to come from the household’s device practices and conversations. Use separate device profiles when possible, avoid sharing login details, and do not assume that a familiar family relationship makes financial access harmless.
The same principle applies to a roommate who asks to “just check something” on your phone. Rent information can reveal more than a due date, and a shared device can blur who is acting on whose behalf. I would keep the account holder in control of account access and use a separate message or document for information that genuinely needs to be shared. This is a small habit, but it prevents coordination from turning into accidental exposure.
Trust is also important because flexible scheduling can make a household feel more organized than it really is. Everyone may see a plan, yet one person could still lack enough money when their part is due. I would review the arrangement regularly rather than assuming the original schedule will remain suitable. A change in work hours, a new lease term, or an unexpected expense can make yesterday’s plan unrealistic.
What the app does well, and where I felt friction
The strongest part of Flex is its narrow purpose. Many finance apps ask users to categorize every purchase, connect multiple accounts, or build a complete budget. That can be useful, but it also creates work. Flex speaks to a specific recurring problem: rent does not always line up neatly with the way people get paid. For someone who needs that adjustment, the focused design is easier to understand than a broad financial dashboard.
Another strength is that it can fit different living arrangements. The app is not limited to a single type of household in the way a roommate spreadsheet often is. A solo tenant with uneven income, a couple with separate finances, and a group coordinating a shared obligation may all find a reason to consider it. The workflow still requires clear agreements, but the underlying idea is flexible enough to apply beyond one household model.
The friction comes from expectations. A user looking for complete bill splitting may be disappointed if they expect Flex to settle every shared expense, track household chores, or mediate roommate disputes. Rent is the center of the product. The more your needs move toward general budgeting, debt planning, or a detailed shared ledger, the more likely you are to need another tool alongside it.
I would also avoid treating the flexible schedule as permission to delay planning. The app can make timing more manageable, but it does not eliminate the consequences of insufficient funds or poor coordination. Before committing, I would make sure the scheduled approach works with the rest of the month’s obligations. If rent is already consuming nearly all available income, changing the dates may provide temporary breathing room without solving the underlying affordability issue.
On the practical side, I would check the current app experience before making it part of a critical payment routine. The application is free, runs on Android versions beginning with 7.0, and its current version is 3.58.0. That makes it accessible to many existing Android devices, but compatibility alone is not a guarantee that an older phone is ideal for managing sensitive finances. Keep the operating system updated when possible, protect the device with a lock screen, and confirm each payment step rather than relying on memory.
How it compares with ordinary alternatives
The usual alternative is a bank’s recurring payment feature. That can be better for a tenant whose only requirement is sending the same amount from the same account on the same date. Bank tools are often familiar and require no separate rent-focused workflow. I would choose that route when the household is simple, the income schedule is stable, and there is no need to rethink the timing.
A shared spreadsheet is more transparent for roommates who need to track uneven shares, utilities, deposits, reimbursements, and historical changes. It offers flexibility that a dedicated rent app may not. Its weakness is that someone must maintain it, check formulas, and make sure everyone is looking at the latest version. Flex has the advantage of focus, while a spreadsheet has the advantage of customization.
General budgeting apps are stronger when rent is only one part of a larger financial plan. They can help users compare housing costs with food, transport, savings, and debt payments. I would use one of those if my main question were “Can I afford my whole month?” rather than “How can I arrange the timing of rent?” Flex is more specialized and may be easier for the second question.
For a household that wants maximum visibility, a shared bank account may appear simpler, but it also combines money and trust in a more direct way. I would not recommend that merely to avoid a conversation about rent. Keeping accounts separate while coordinating a housing payment can be safer for some roommates, especially when the relationship is new. Flex fits that middle ground better than pooling everything, provided each person understands the arrangement.
Who should use it, and who should skip it
I would recommend Flex to a renter whose income dates do not match the normal rent cycle, especially when that mismatch creates repeated short-term stress. It also makes sense for roommates or partners who want to coordinate rent without merging all their finances. The app’s free availability lowers the barrier to trying a focused rent workflow, and its broad content rating makes it approachable for households with different ages, although financial responsibility still needs adult judgment.
I would skip it if the only problem is remembering a due date. A calendar reminder, standing bank payment, or existing budget may solve that more simply. I would also look elsewhere if I needed a full household ledger, detailed shared-expense tracking, or a complete financial plan. Adding Flex to an already well-organized system could create another place to check without adding much value.
It is also not the right answer for a household that has not agreed on the basic split. If roommates are still debating whether one person should pay more for the larger room, no scheduling tool can settle that fairly. Decide the responsibility first, then use an app to support the agreement. This order matters more than the interface.
My household verdict
Flex is a specialized finance app with a clear reason to exist. Its central idea is useful because rent timing can be a genuine problem even when the total amount is known and the household is responsible. I like that it focuses on a recurring housing obligation instead of asking users to rebuild their entire financial life inside one application.
My recommendation comes with a boundary: use it as a rent-scheduling aid, not as the household’s only source of financial truth. Keep the personal account protected, record roommate shares separately when necessary, and review the arrangement whenever income, lease terms, or household membership changes. Those habits make the app more dependable and prevent a flexible schedule from hiding an unaffordable commitment.
Flexible Finance, Inc. has built something that will be most valuable to people who feel squeezed by timing rather than confused by budgeting. With an average rating of 4.7 from around 122 thousand ratings and more than a million installs, it has clearly attracted substantial interest from renters. The app is free, and it was released on May 22, 2019, so it is an established option rather than a brand-new experiment.
In my experience, the deciding question is simple: do you need rent to fit your schedule, or do you need a broader system for managing money and people? If the first answer is yes, Flex is worth considering. If the second is yes, I would pair it with a budgeting or shared-record tool, or choose an alternative that already handles those wider needs. Used within those limits, it can make a tense monthly task feel more deliberate and easier to coordinate.


